

Dollarbird Pro
3.3

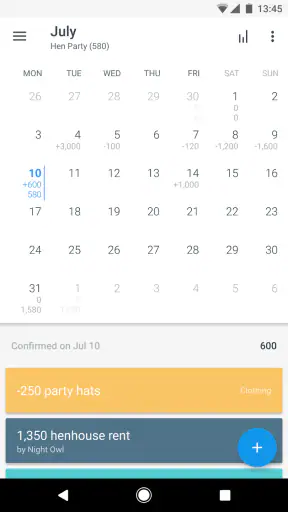
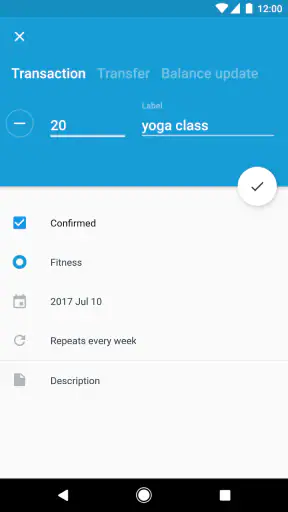
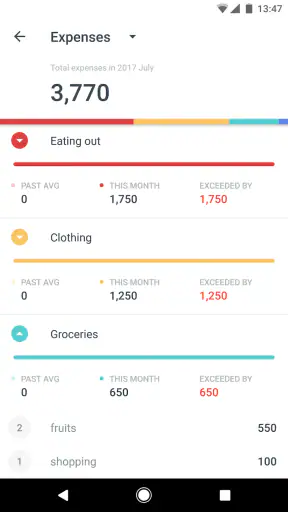
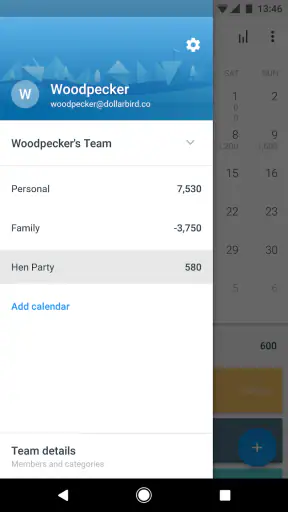
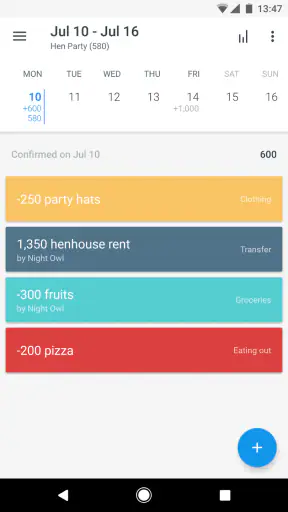
I found Dollarbird Pro most useful when I stopped treating it like a traditional expense tracker and started using it as a forward-looking money calendar. That distinction matters. Instead of only asking where my money went, I could organize expected income, bills, and everyday spending around the dates they affect my balance. For anyone who regularly reaches the end of the month wondering why the account feels tighter than expected, that calendar-first approach is the app’s strongest idea.
It is a free finance app from Dollarbird Apps SRL, aimed at everyday personal budgeting rather than investing, banking, or complicated accounting. The store presents it as a personal finance calendar with an AI element, while the short store label is Dollarbird Pro. Its current version is 6.2.2, and it runs on Android from version 6.0 onward. The app is rated for Everyone, so the basic concept is accessible even if the way you use it becomes more sophisticated over time.
Why the calendar approach works better than a simple spending list
Most budget apps begin with categories: food, transport, rent, entertainment, and so on. Those categories are useful, but they do not always answer the question I actually have before payday: “What will my balance look like after the next few bills?” Dollarbird’s calendar view puts timing at the center. I can look at a particular day, see what is expected to happen, and understand how several small decisions may combine before the next income arrives.
That makes the app especially practical for recurring commitments. Rent, subscriptions, loan payments, school costs, and regular transfers are easier to understand when they are placed on the dates they usually leave the account. I found that this encouraged a different habit from ordinary expense tracking: I was planning around cash flow instead of merely recording the past.
The distinction between a planned transaction and a completed transaction is important here. A calendar forecast is only useful if I keep it honest. When a payment changes, arrives early, or costs more than expected, I need to update the entry rather than assume the original estimate still represents reality. That small discipline is also the app’s hidden cost: Dollarbird can make future money clearer, but it cannot maintain an accurate forecast without regular attention.
For a realistic example, imagine a household paid near the middle of the month. The rent is due shortly afterward, a utility bill varies, groceries are spread across several shopping trips, and a streaming subscription is charged near the end of the cycle. A conventional list may show that spending is “within budget” overall. A calendar can reveal that the first week after payday is unusually crowded, while the final week is comfortable. That insight can change when I shop, transfer money, or postpone a nonessential purchase.
Entering transactions without turning budgeting into paperwork
The best way to use this app is to keep entries useful rather than obsessively perfect. I would begin with the transactions that control the month: income, housing, utilities, debt payments, insurance, and other predictable commitments. Once those are visible, I would add flexible areas such as food and transport. Entering every tiny purchase can help some people, but it can also make the calendar noisy and discourage continued use.
A practical workflow is to make a short weekly review part of the routine. I would compare the calendar with my bank balance, mark completed items, correct changed amounts, and add any unusual expense that could affect the next few days. This is more valuable than spending an hour at the end of the month trying to reconstruct everything from memory. The app works best as a living forecast, not as a diary that is updated only after the money is gone.
Another useful technique is to separate certainty from estimation. A fixed rent payment can be treated as dependable, while a grocery amount or utility bill should be viewed as a forecast. If I enter both with the same confidence, the resulting balance may look more precise than it really is. I would rather use a slightly cautious estimate for variable expenses and then adjust it when the real amount becomes known.
The calendar also helps expose “small but badly timed” spending. A purchase does not need to be large to create a problem if it lands between several scheduled payments. Looking at the sequence of transactions makes that pattern easier to notice than a monthly category total does. This is one of the app’s more meaningful strengths, and it is easy to miss if I use it only as a place to record receipts.
Where the AI angle helps, and where I stay cautious
The app’s store summary mentions a spark of AI, but I would not choose it solely because of that phrase. The useful question is whether the intelligent assistance makes planning faster or clearer in my own routine. For me, the calendar remains the main reason to use Dollarbird. The AI element is secondary: helpful when it reduces friction, but not a substitute for checking dates, amounts, and account reality.
That is also where I would keep expectations realistic. Personal finance is sensitive to context. An automated suggestion may not understand that a payment was intentionally moved, that an irregular bill is annual rather than monthly, or that two people share responsibility for one expense. I would review any automated interpretation before relying on it. The app can support judgment, but it should not become the authority deciding whether money is available.
Users who enjoy a quick, guided way to make sense of their entries may appreciate the intelligent touch. Users who prefer complete manual control may find the traditional calendar functions more important than the newer assistance. Either way, the strongest experience comes from combining the app’s organization with my own verification rather than expecting automation to solve inconsistent records.
The meaningful weakness: forecasting depends on maintenance
Dollarbird’s central strength creates its central limitation. A calendar forecast looks reassuring when it is current, but it becomes misleading when old estimates remain untouched. Variable bills, cash purchases, refunds, shared expenses, and delayed charges can all weaken the picture. I would not use the projected balance as a guaranteed statement of what my bank account contains.
This may frustrate people who want automatic, hands-off synchronization with their financial life. Dollarbird is better suited to someone willing to participate in the process. If I want an app that imports transactions, categorizes them automatically, and gives me a near-zero-maintenance spending report, a bank-connected tracker may be a better fit. The trade-off is that manual planning can be more intentional and less dependent on exposing account activity to another service.
There is also a learning curve in deciding how much detail belongs on the calendar. Too little information leaves gaps; too much makes the view difficult to read. I would avoid creating separate entries for every minor item at first. Start with the transactions that affect timing, then add detail only when it answers a real question. That keeps the system manageable and makes the forecast easier to trust.
The average rating is 3.3 from around 600 ratings, with over 100 written reviews, which suggests that the experience is not universally smooth. I would read that as a reason to approach the app with the right expectations rather than as an automatic rejection. Calendar-based budgeting is a particular method. People who want a different method may judge the app harshly even though its underlying idea suits another kind of user very well.
Who will get the most from this finance app?
I think Dollarbird is a strong candidate for people with regular income and several recurring obligations who want to see the month as a sequence of financial events. It is particularly suitable for anyone who has enough money overall but occasionally struggles with timing. Freelancers and people with irregular income may also benefit, although they will need to enter forecasts carefully and update them more often.
It can be useful for couples or households that plan together, provided everyone agrees on how transactions should be represented. A shared calendar can clarify which expenses are expected and when, but it does not remove the need to communicate. If one person records a shared bill and another records only their portion, the forecast can become confusing. Establishing a simple rule before adding entries is more important than adding more categories.
Students and first-time budgeters may find the visual timeline less intimidating than a spreadsheet. Instead of building formulas, they can begin by placing income and unavoidable costs on the calendar. The method teaches an important financial lesson: having enough money for the month is not the same as having enough money on every date within the month.
On the other hand, I would skip it if my main goal were investment tracking, detailed business bookkeeping, tax preparation, or deep analysis of historical spending. Those tasks demand tools built around portfolios, invoices, reports, or account aggregation. Dollarbird’s value is narrower and clearer: it helps me think about personal cash flow through time.
Free access, paid options, and what to consider before committing
The app is free to download, which makes it easy to test the calendar method without an upfront purchase. It also includes in-app purchase options ranging from $7.99 to $79.99 per item. Because the right choice depends on the plan and features presented inside the app, I would first use the free experience with a realistic month of transactions. That tells me whether the workflow itself fits before I spend money on additional access.
I would pay only if the app becomes part of a dependable routine and the paid features remove a genuine obstacle. A budget tool is not valuable because it contains more screens; it is valuable when I actually open it, understand the forecast, and make better decisions. If the calendar feels like work after a short trial, purchasing more capability will not fix the basic mismatch.
Privacy-minded users may also prefer the deliberate nature of entering financial information themselves, but manual control comes with responsibility. I would avoid entering sensitive notes that are unnecessary for budgeting, and I would keep the app’s records aligned with what I really need to remember. The most useful entries are usually dates, amounts, and clear descriptions—not a complete personal history.
How it compares with spreadsheets and automatic trackers
A spreadsheet remains more flexible. I can create custom formulas, build reports, and adapt the layout to unusual financial situations. However, spreadsheets often require more setup and are less pleasant for quick daily updates. Dollarbird gives the calendar idea a dedicated home, so the central view is easier to maintain than a workbook that I designed from scratch.
Automatic bank trackers have the opposite advantage. They reduce manual entry and can be excellent for reviewing what already happened. Their weakness is that imported history does not always make future timing obvious, especially when income and bills fall on different dates. Dollarbird’s manual forecast can be more useful before a transaction occurs, as long as I accept the effort of keeping it current.
Traditional envelope-style budget apps are better when the question is how much remains in each spending category. Dollarbird is better when the question is whether the balance can survive the next sequence of dates. These are not interchangeable priorities. Someone who constantly overspends on dining may need category limits first; someone who pays bills on time but repeatedly misjudges the middle of the month may benefit more from the calendar view.
My practical setup for a first month
I would begin by entering the next income date and the largest fixed commitments. Then I would add recurring bills, using conservative estimates for anything that changes. After that, I would place a reasonable allowance for flexible spending across the relevant days rather than pretending every purchase is known in advance.
During the first week, I would watch for friction. Are entries quick enough? Does the calendar answer my main cash-flow question? Do I understand which items are forecasts and which have actually happened? If the answer is yes, I would continue for a full cycle before deciding whether the app deserves a permanent role.
At the end of that cycle, I would review surprises rather than chase perfect accuracy. Which payment arrived on a different date? Which estimate was too optimistic? Which small expense repeatedly appeared at inconvenient times? This turns the app into a planning tool instead of a scorecard. The goal is not to predict every cent; it is to make future pressure visible early enough to respond.
Dollarbird Pro is available as a free app and has passed the fifty-thousand-install mark, giving it a meaningful user base without making it feel like a universal finance platform. Its Everyone age rating also makes the basic budgeting concept approachable for a broad audience. Still, the most important decision is not popularity. It is whether I prefer a hands-on calendar to an automated transaction feed.
My final view is positive but specific: Dollarbird is best when timing is the problem, not when detailed financial analysis is the goal. I like the way it encourages me to look ahead, especially around paydays and recurring bills. I also respect its limits. The forecast needs maintenance, the AI touch should be treated as assistance rather than financial advice, and people seeking automatic bank synchronization or professional-grade reporting should choose another category of tool.
If I were recommending it to a friend, I would say this: try the free version with your real upcoming bills, keep the first calendar deliberately simple, and judge it by whether it changes a decision before the money leaves your account. If that forward-looking view feels natural, Dollarbird Pro can become a practical companion for everyday planning. If you only want an effortless record of past spending, a conventional tracker will probably serve you better.
3.3
128.00 Reviews
Pros
- Calendar-based design makes recurring income and expenses easy to visualize.
- Shared calendars help households or teams coordinate budgets in one place.
- Custom categories make it easier to identify spending patterns over time.
- Cloud syncing keeps financial records available across supported devices.
- Future balance projections can help with planning upcoming bills and purchases.
Cons
- Manual transaction entry can become tedious for frequent daily spending.
- The subscription cost may not appeal to users seeking a completely free budget app.
- Limited automation may require more effort than apps with bank synchronization.
- Shared finances can become confusing without clear rules for editing transactions.
- Currency and regional support may vary depending on the account setup.


